Three More Repo Rate Hikes Projected: Home Loan EMIs Face Upward Pressure
Three More Repo Rate Hikes Projected: Home Loan EMIs Face Upward Pressure
On 18 November 2026, Goldman Sachs projected three more 25 basis point hikes in the RBI repo rate, which would take it to 6.25%. The repo rate currently stands at 5.50%, and the first hike in this cycle came on 7 October 2026. For homebuyers and investors in India, this is a signal that the cost of home loans is likely to keep climbing into 2027.
The Story
The RBI's Monetary Policy Committee met from 5 to 7 October 2026 under Governor Sanjay Malhotra and raised the repo rate by 25 basis points, from 5.25% to 5.50%. It was the first increase since February 2023. The vote was unanimous at 6-0, and the stance moved from neutral to calibrated tightening. The central bank pointed to elevated inflation, global geopolitical tensions, higher energy prices and a deficient south-west monsoon as the reasons behind the move.
India's CPI inflation rose to 6.1% in October 2026, up from 5.5% in September and above the upper end of the RBI's 2-6% tolerance band. Goldman Sachs now expects headline inflation to stay slightly above 6% through the fourth quarter of 2026 and the first quarter of 2027. Its baseline includes one more 25 basis point hike in December 2026 and about 50 basis points of further tightening in the first half of calendar 2027. The RBI's own revised forecast for FY2026-27 puts CPI inflation at 5.2%, while real GDP growth is seen at 7.1%. The next scheduled MPC meeting is on 2-4 December 2026.
What This Means If You're Buying
A repo rate hike does not change property prices overnight, but it does change the monthly outgo of anyone borrowing to buy a home. Floating-rate home loans reprice at the next interest reset, so existing borrowers will see their EMIs rise once lenders pass the hike on. As an illustration cited by BASIC Home Loan, a 25 basis point increase on a ₹50 lakh, 30-year loan adds about ₹852 a month at a PSU bank and about ₹867 a month at a private bank.
Goldman Sachs expects the tightening to weigh on credit growth, which has been strong until now. That matters for buyers because the housing market runs on mortgage finance. Industry voices differ on how deep the impact will be. CREDAI President Shekhar Patel said the increase could affect sales during the festive season, though underlying demand remains firm. Colliers India's Vimal Nadar expects a softening in near-term demand, while CBRE India's Anshuman Magazine said the impact is likely to stay measured, particularly in the mid and premium segments. Suresh HA of Sanjeevini Group warned that further hikes could strain affordability for first-time and finance-dependent buyers, who have the least room in their budgets.
Synergy Infracon's Take
We read this news as a tightening cycle that is being driven by inflation and supply shocks rather than by any weakness in housing demand. That distinction matters. The developers and channel partners we work with are reporting that the mid and premium segments hold up better when rates rise, because those buyers tend to be less dependent on stretched loans. Where we agree with the more cautious voices is on first-time buyers. A family stretching to the limit of its loan eligibility feels a 25 basis point move far more sharply than a buyer with a large down payment. In our view, the market reaction over the next two quarters will be more about timing and negotiation than about outright price falls. Buyers who have already done their numbers at 5.50% should stress-test their EMI at 6.25% before committing, rather than assuming the current rate will hold.
What We'd Advise Right Now
- Run your EMI at the current rate plus 75 basis points. If the monthly figure still fits your budget comfortably, the projected hikes are manageable for you.
- Compare fixed and floating loan offers carefully. Floating loans reprice with each reset, so a lender's spread and reset terms matter as much as the headline rate.
- Do not wait for a rate cut to make a decision. The December 2 to 4 MPC meeting is the next checkpoint, and the current outlook points to hikes rather than relief.
- Focus on the mid and premium segments in established localities, where demand has shown more resilience through past rate cycles, and check possession timelines and payment schedules closely.
- Talk to our sales team before booking. We can model your loan options against the projects you are considering and help you avoid a commitment that only works at today's rate.
Related Projects We Cover
- Godrej Hebbal, Bengaluru: a useful benchmark for buyers testing a Bengaluru north-side budget against higher EMIs.
- Tata Doddanekundi Whitefield, Bengaluru: worth comparing against other Whitefield options if your loan is sized close to its limit.
- Prestige Kharadi, Pune: a Kharadi option for buyers weighing Pune's IT-corridor demand against tighter lending.
- Hiranandani Hinjewadi, Pune: relevant for buyers who want to see how Hinjewadi pricing responds as lending costs rise.
Projects mentioned in this article
Godrej Hebbal
by Godrej Properties
Hebbal, Bengaluru
Price on Request
2 BHK, 3 BHK (expected, subject to change at launch)
 Pre-Launch
 Upcoming
Tata Doddanekundi Whitefield
by Tata Realty
Doddanekundi, Bengaluru
From ₹1.60 Cr
2 BHK, 3 BHK, 4 BHK
 New Launch
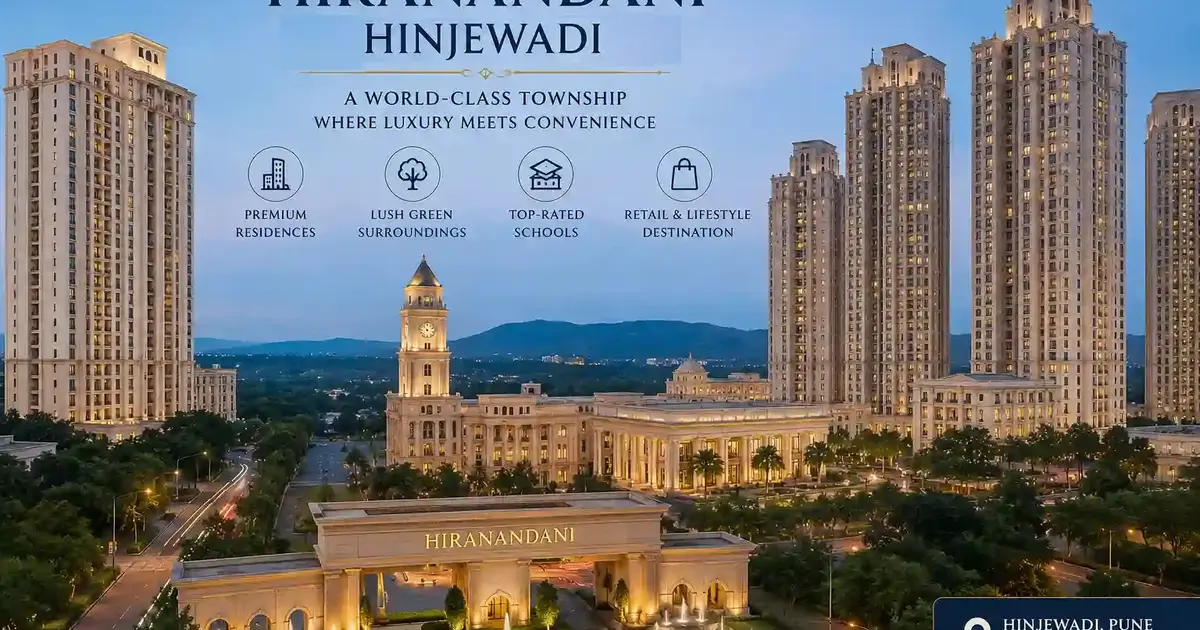
Hiranandani Hinjewadi
by House of Hiranandani
Hinjewadi, Pune
₹78.99 Lakh - ₹1.85 Cr
2 BHK, 3 BHK, 4 BHK and duplex
Developers mentioned

Hiranandani

Sanjeevini Group
Locations covered
Cities
Localities
Related News
 Investment
SEBI Clears Bengaluru Developer Assetz for ₹1,200 Crore Share Sale
Bengaluru Developer Assetz Moves Closer to Listing With SEBI Clearance Bengaluru-based residential developer Assetz has received final observations from the...
 New Launch
Puravankara Launches 1,056 Homes in Edappally With Phases Running to 2033
Purva Cityspire in Edappally, Kochi: 2 and 3 BHK homes from 1,271 to 1,895 sq ft, priced from ₹1.44 crore, launched 18 November 2026 by Puravankara.
 Policy
Goa's Mhajo Flat Scheme Opens Path to Legal Title for Unregistered Flats
Goa launches the Mhajo Flat scheme for flat owners with unregistered titles. Deemed conveyance, concessional stamp duty and a pre-election target.
 Market Update
Bengaluru's Hebbal-Sarjapur Metro Slips to April 2033 as Costs Are Revised
Bengaluru's Hebbal-Sarjapur Metro Phase 3A now targets April 2033 and a ₹25,999 crore cost. Here is what the delay means for home buyers and investors.